
The oddities in the US labor market continue.
Article by Tyler Durden at Zero Hedge.
Recall one month ago we showed that a stark divergence had opened between the Household and Establishment surveys that make up the monthly jobs report, and since March the former was sliding while the latter was rising every single month. In addition to that, full-time jobs were plunging while multiple jobholders soared near all time highs.
Fast forward to today when the inconsistencies grow and in some cases have becoming downright grotesque.
Consider the following: the closely followed establishment survey came in above expectations at 315K, yet it was well below last month’s 526K print, with June unexpectedly revised sharply lower by 105K from 398K to 293K…
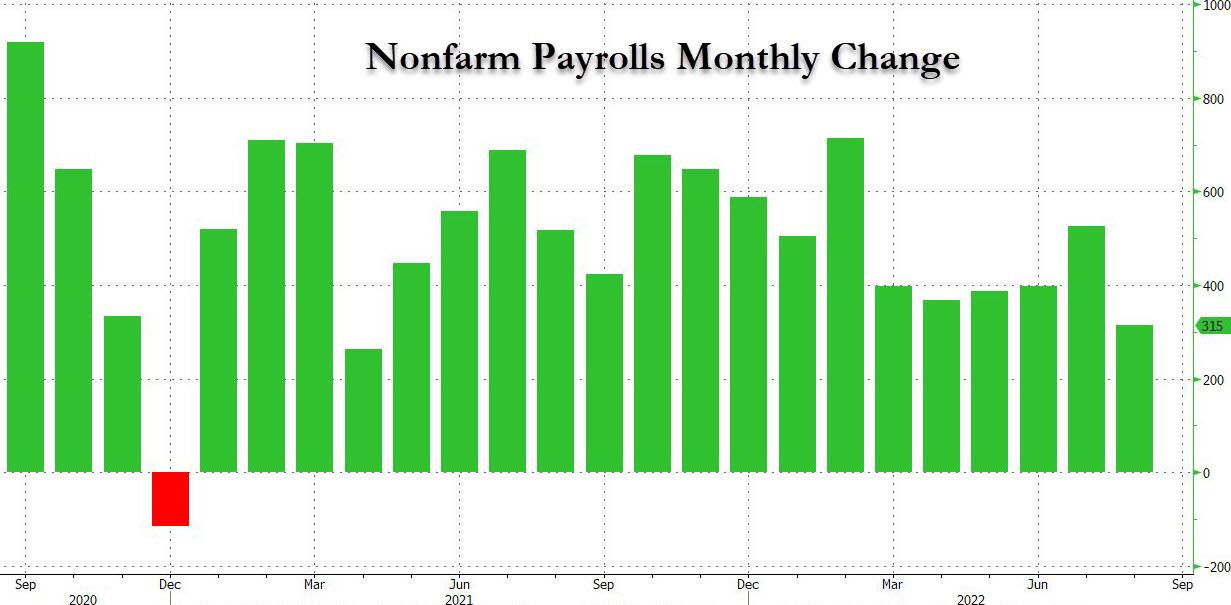
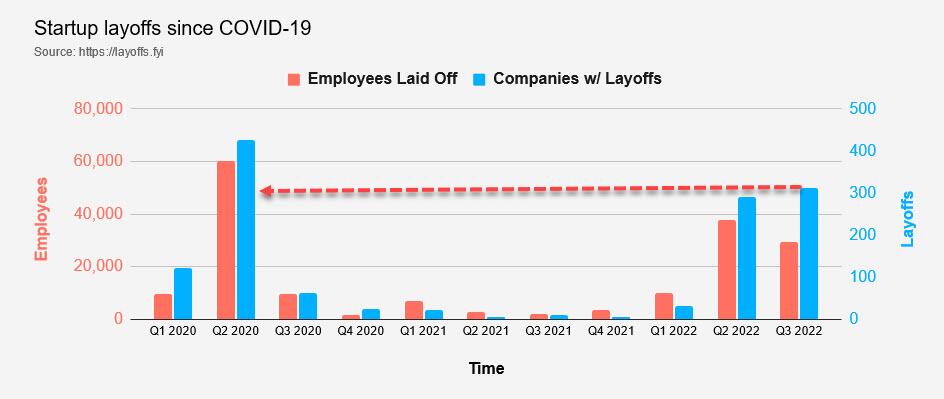
… revisions which will go toward reducing the huge gap that has grown between the Household and the Establishment survey, although not nearly enough and as Academy Securities’ strategist Peter Tchir writes, “look for more revisions as last month’s surprisingly good result wasn’t revised much.” Of course, there is a problem with the above: all of these numbers are complete bullshit, and to believe them, one has to disregard and ignore the mass layoffs announced by US corporations and tracked by handy third-party websites such as Layoffs which shows that in recent months and quarter, the US has been swept by near record layoffs, on part with those observed during the peak of the covid crisis!
And speaking of the gap between the Household and Establishment survey which we have been pounding the table on in recent months, it narrowed modestly thanks to a 442K jump in the number of employed workers (tracked by the Household survey) offsetting a more modest increase in employment, which rose 315K (tracked by Establishment survey). And while the rebound in the Household was long overdue, there is a long way to go as the following chart shows, demonstrating that the gap that opened in March has since grown to a whopping 1.6 million “workers” which may or may not exist anywhere besides the spreadsheet model of some BLS political activist.
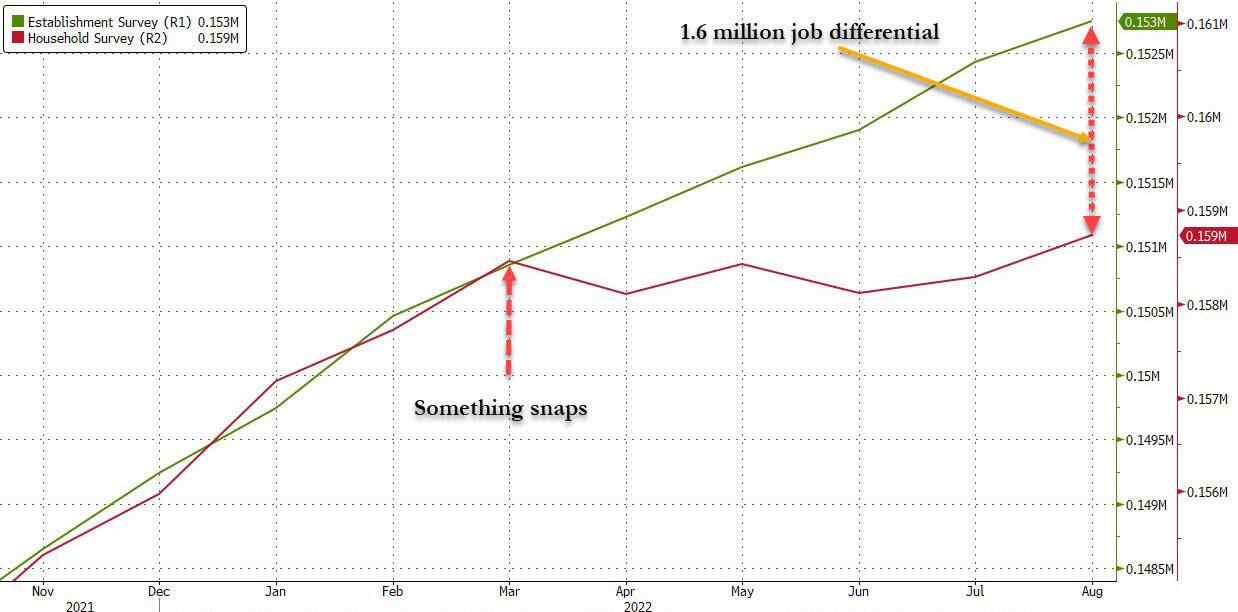
Of course, there is a reason why the Household survey would want to take its time in catching up to the establishment survey: since the direct variable in the red line above is the number of employed workers, which in turn drive the number of unemployed workers and thus, the unemployment rate (as a function of the civilian labor force), any overly aggressive increases here will lead to a disproportionate increase in the unemployment rate. So Biden’s apparatchiks have to pick their poison.
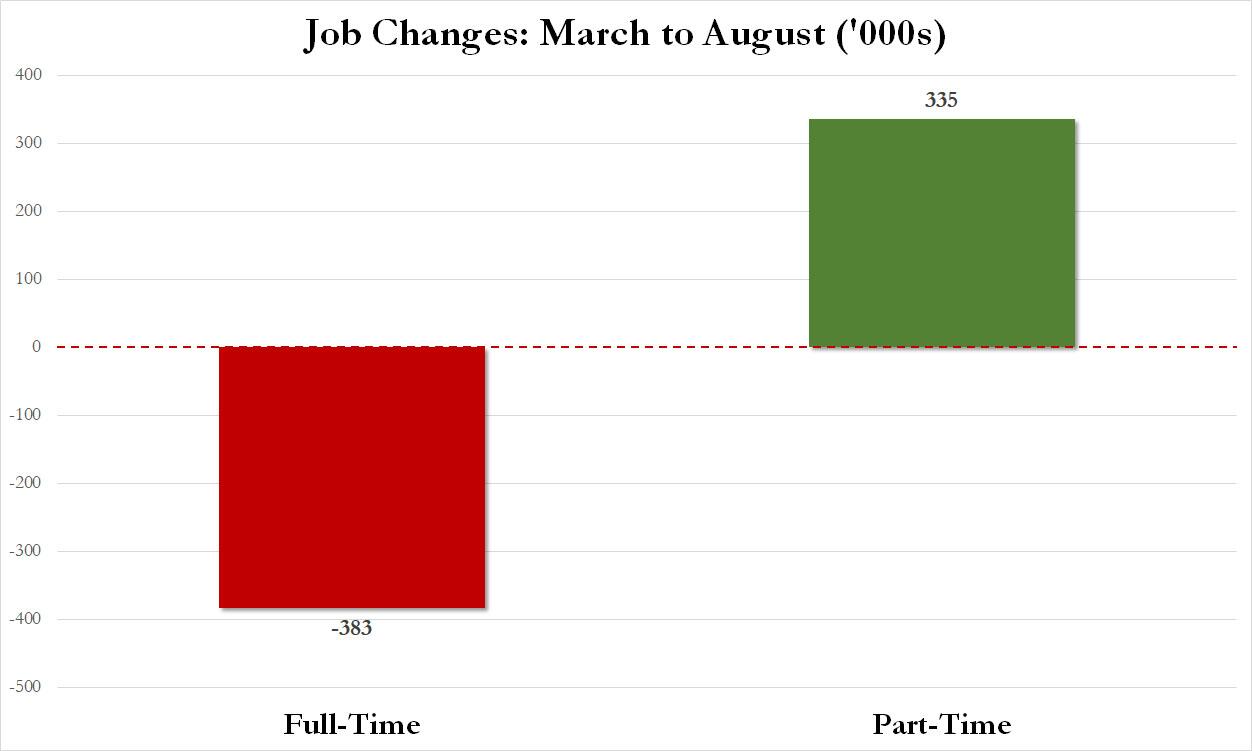
But wait, there’s more because digging deeper, we find that the latest (overdue) jump in Household Survey employment was entirely the result of rising part-time jobs, which surged by 413K in August, while full-time jobs declined by 242K.

More ominously, if one extends this data, we find that since March, the US has lost 383K higher paying full-time employees, while gaining 335K low-paid part-time employees. Again, this is a time period over which the Establishment survey claims – without a breakdown in job quality – that 1.9 million total jobs have been added.
And even more remarkable: the number of multiple jobholders whose primary and secondary jobs are both full-time just hit another record high! Hardly the sign of a strong job market, one where people can afford to quit jobs at will.
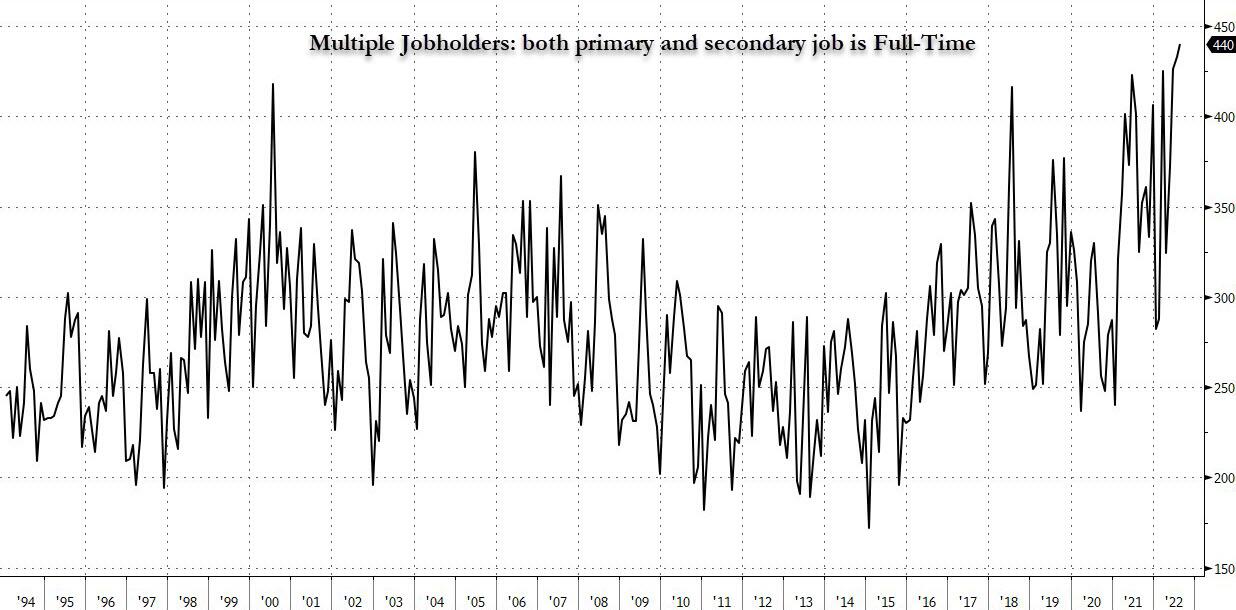
So what’s going on here? The simple answer: Fewer people working, but more people working more than one job, a rotation which picked up in earnest some time in March and which has only been captured by the Household survey.
And since the Establishment survey is far slower to pick up on the nuances in employment composition, while the Household Survey has gone nowhere since March (which has benefited the low unemployment rate), the BLS data engineers have been busy goalseeking the Establishment Survey (perhaps with the occasional nudge from the White House especially now that the economy is in a technical recession) to make it appear as if the economy is growing strongly, when in reality all they are doing is applying the same erroneous seasonal adjustment factor that gave such a wrong perspective of the labor market in the aftermath of the covid pandemic (until it was all adjusted away a year ago). In other words, while the labor market is already cracking, it will take the BLS several months of veering away from reality before the government bureaucrats accept and admit what is truly taking place.
We expect that “realization” to take place a few hours after the midterms, because the last thing the Biden administration can afford is admit the labor market is collapsing at a time when true inflation – the one tracking items most people spend their money on – is not 8.5% but is over 30%…
Inflation for items most people spend majority of their income on 👇 8,5% wouldn’t be that bad. (Charles Schwab) pic.twitter.com/pWQs5OApDF
— Michael A. Arouet (@MichaelAArouet) August 11, 2022
Two Storms, One Harvest

Every food crisis in living memory has been a one-shock event. The 2008 price spike was a commodity bubble. The 2020 shortages were a logistics failure. The 2022 grain scare was a war on one exporter’s ports. Each time, the system bent, adjusted, and recovered, and each time the experts assured us afterward that global markets are simply too big and too diversified to fail.
What nobody in Washington seems eager to discuss is that 2026 is shaping up to be something the modern food system has never actually faced. Two independent shocks, one climatic and one geopolitical, are converging on the same harvest cycle at the same time. Not sequentially. Simultaneously.
Start with the weather. The Pacific Ocean is currently building toward what forecasters now openly call a record event. NOAA’s Climate Prediction Center puts the odds of at least a strong El Niño near 88 percent, with roughly two in three odds it reaches “very strong” status, the tier reserved for perhaps three or four events in the entire satellite era. Every major global model now projects a median peak in Super El Niño territory, and most of them project it exceeding the 2015-16 event, which until now held the modern record. Sea surface anomalies were already brushing the super threshold in mid-July, months before these events normally peak. The atmosphere has already shifted into El Niño mode, and the event is forecast to crest in late fall and early winter.
This is not about “climate change.” It’s about the standard cycles of weather, and the cycle we’re currently in is one that has likely devastated societies in the past. We’re better prepared as a society today, but not all Americans are equally prepared.
Serious households have started doing the quiet math on their own. Grocery bills tell part of the story, and the forecast maps tell the rest, which is why long-term food storage has moved from fringe hobby to mainstream line item in the family budget, with established suppliers like Heaven’s Harvest seeing demand from people who five years ago would have rolled their eyes at the idea. That instinct is not paranoia. It is pattern recognition, and the pattern is worth walking through carefully.
Editor’s Note: Heaven’s Harvest IS a sponsor, but the warnings of this article are real and would be written even if we didn’t have a survival food sponsor. With that said, those who take advantage of what they offer can use promo code “Patriot” for 15% off.
The Fertilizer Clock Is Already Running
While the Pacific warms, the second shock has been unfolding in the Strait of Hormuz. The conflict with Iran turned the world’s most important energy chokepoint into a contested waterway, and the consequences reach far beyond the gas pump. Roughly a third of global fertilizer trade moves through Hormuz, and the disruption sent urea prices up 86 percent year over year by March, with a 53 percent jump in a single month.
The World Bank projects energy prices rising about 24 percent in 2026 and fertilizer about 31 percent. By its own accounting, fertilizer prices ran 35 percent higher in the first five months of this year than the same period last year.
Here is the mechanism the nightly news will not explain. Fertilizer is not a grocery item. It is a time-delayed input. The nitrogen a farmer in Iowa or Punjab could not afford to apply this spring does not show up as a problem this spring. It shows up as a thinner harvest six to twelve months later.
The World Bank’s own food security brief concedes that the effects of reduced applications earlier this season “are likely to become visible only later in harvest outcomes.” Translate that from institutional language into plain English and it means this. The damage is already done, it is already in the ground, and we are simply waiting for it to arrive on the shelf.
Now check the calendar. Six to twelve months from the spring planting season lands us squarely in late 2026 and early 2027. Which is precisely when the strongest El Niño in the instrumental record is forecast to peak, bringing its signature droughts to Southeast Asia, Australia, southern Africa, northern Brazil, and South Asia, the very regions that grow the world’s rice, sugar, and oilseeds.
The World Bank warns openly that a strong El Niño “could disrupt multiple crop belts simultaneously” on top of the conflict-driven input costs. Their baseline projection assumes the Middle East disruptions ease by autumn. What in the last two years of Middle East history suggests that assumption is safe?
The System Has No Slack Left
The comfortable answer is that global markets always adjust. But adjustment requires slack, and the slack is gone. Global cereal production is expected to decline from last year’s records even before El Niño does its work. The UN World Food Programme, hardly a den of right-wing preppers, is calling this the most significant disruption to its supply chains since Covid and the invasion of Ukraine, and its supply chain director put the stakes bluntly.
Today’s supply chain challenges are tomorrow’s hunger crisis.
There is also a political dimension that markets cannot price. When food gets scarce, governments do not behave like economists. They behave like politicians. Export bans, hoarding mandates, and panic buying at the national level turned the modest rice shortfall of 2008 into a global crisis, and analysts are already warning that import-dependent nations are the first dominoes.
The 2015-16 Super El Niño, a far weaker event than what is now forecast, threw tens of millions into food stress across Africa and Asia. This one is projected to be stronger, and it arrives with fertilizer already rationed by price and shipping lanes already contested by missiles.
What Joseph Knew
Scripture does not treat preparation for lean years as faithlessness. It treats it as wisdom delivered in advance to those willing to act on it.
Behold, there come seven years of great plenty throughout all the land of Egypt: And there shall arise after them seven years of famine; and all the plenty shall be forgotten in the land of Egypt.
Joseph did not respond to that warning with a hashtag or a committee. He stored grain during the years of abundance, and when the famine came, Egypt stood while its neighbors begged. The lesson is not that famine is certain. It is that the time to prepare is precisely when preparation still looks optional.
Nobody who filled a pantry in a year of plenty has ever regretted it, and nobody standing in an empty aisle has ever been glad he waited for certainty.
None of this calls for panic, and panic is the enemy of sound judgment anyway. It calls for the same unglamorous prudence our grandparents considered ordinary. Keep some cash margin, know your local growers, and put real food in deep storage while it is cheap and available, because the entire arc of this story is that cheap and available is a closing window.
Families looking for a straightforward place to start can visit Heaven’s Harvest and use promo code Patriot for 15 percent off long-term storable food. The forecasts may yet soften, the strait may yet reopen, and we should pray they do. But hope is a fine thing to hold and a foolish thing to eat.
